I once knew a guy named Dave who bought a 2005 Hyundai Elantra for $900. The paint was peeling, the radio only played static, and the AC smelled like a wet sock. But Dave’s insurance was so cheap, he could afford to buy a better Bluetooth speaker to drown out the static.
Older, cheaper cars often come with lower insurance premiums because you’re only insuring against damage to others, not to your own rolling scrap heap. If you total it, you shrug and walk away. You don’t cry over a smashed toaster. The key is to find a car that’s safe, not sexy. A 2012 Kia Rio? Boring. Your bank account? Thrilled.
Don’t fall for the trap of a 2002 Mustang just because it’s cheap to buy. That car is a magnet for insurance surcharges. It’s like buying a cheap pizza—the cost seems low, but you’ll pay for it later in heartburn and regret.
What Actually Makes the Price Drop?
Here’s the secret sauce: cars with good safety ratings and low horsepower are insurance gold. A Subaru Impreza? Solid. A Ford Fiesta? Score. A Dodge Charger with a V8? That’s a personal finance crime. Insurers use a simple formula: more power equals more panic for them.
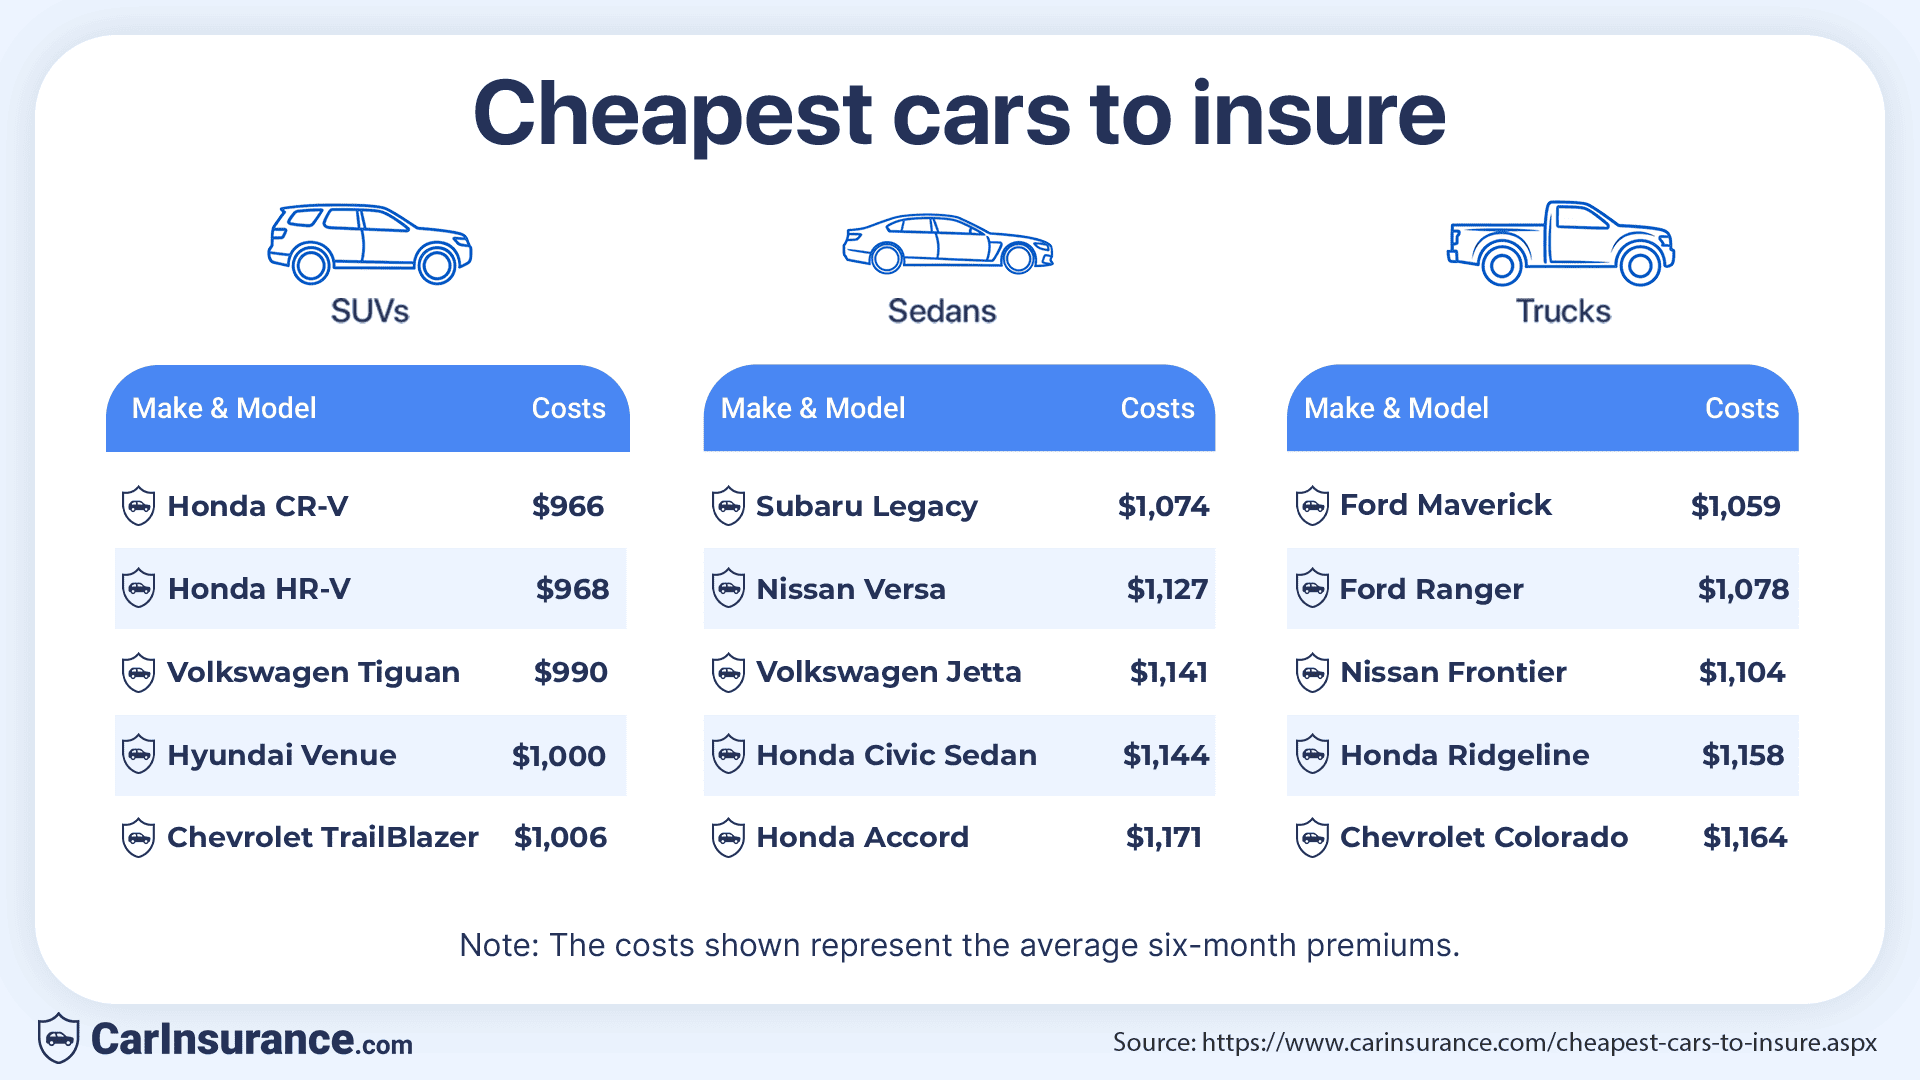 Get Free Car Insurance Quotes in the USA for 2026 | CarInsurance.com
Also, look for cars that are annoyingly common. If a car is everywhere (like a Honda CR-V), parts are cheap, and mechanics know them like their own kids. That means lower repair costs, which means lower insurance for you. It’s the same logic as ordering the cheapest item on the menu—nobody raves about it, but nobody cries over the bill.
I remember my first car was a 1999 Saturn SL1. It was the color of faded mustard. I named it “The Scooter.” It had no airbags in the back and the engine sounded like a lawnmower with a cold. But my insurance was $80 a month. Eighty dollars. I drove that sad little box like it was a chariot, because it was the only chariot I could afford to crash.

