
So, just how much can paying off a loan improve your credit score? The answer is, it depends on a few factors, like the type of loan and your overall credit profile. But, in general, paying off a loan can lead to a significant increase in your credit score - we're talking 50-100 points or more! It's like getting a free upgrade to first class, financially speaking!
Now, let's talk about the different types of loans and how paying them off affects your credit score. For example, paying off a credit card can have a bigger impact than paying off a personal loan, since credit card debt is often seen as higher risk. It's like playing a game of financial chess - you need to know the right moves to make!
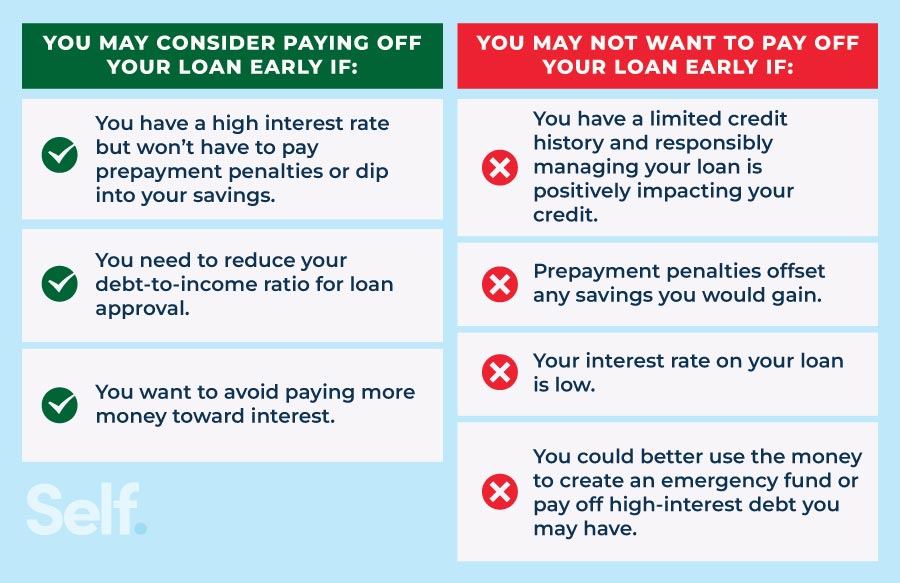 Does Paying Off a Loan Early Hurt Your Credit? Here's What to Know
But, here's the thing: paying off a loan isn't just about improving your credit score - it's also about freeing up cash flow and reducing your debt-to-income ratio. It's like breaking free from the chains of debt and starting fresh, financially speaking! So, go ahead and pay off that loan - your credit score (and your wallet) will thank you!
In conclusion, paying off a loan is a great way to improve your credit score and get your finances on track. It's like leveling up in the game of adulting, and who doesn't love a good upgrade? So, go ahead and pay off that loan, and watch your credit score soar like a financial eagle!

