
So, you got the ticket. It’s done. Now what? First, don’t just pay it blindly. In many states, you can take a defensive driving course to have the ticket dismissed or the points reduced. This is your get-out-of-jail-free card, and it usually costs less than the premium hike.
Second, shop around for a new policy after the ticket hits your record. Not all insurers treat speeders the same. Some, like GEICO or Progressive, are more forgiving than others, especially if you’ve been a loyal customer.
Third, ask about accident forgiveness or ticket forgiveness programs. Many companies offer these as add-ons for a few extra dollars a month. If you have a tendency to play “lead foot” at stoplights, this is your safety net.
The Cultural Speed Trap
You know who else understands this pain? The cast of Top Gun—Maverick might feel the need for speed, but he’d still cry when the insurance bill arrives. Pop culture romanticizes fast driving, but real life is about that spreadsheet.
There’s even a study that found men under 25 see the highest rate spikes, because insurance companies look at demographics like a stern uncle. It’s not personal; it’s math. If you’re a female driver over 40, your bump might be half that.
And here’s a weird twist: if you live in a state like Michigan or Louisiana, your rates are already sky-high, so a ticket might feel like adding a cherry to a sundae you never ordered. In Maine? That same ticket could feel like a financial earthquake.
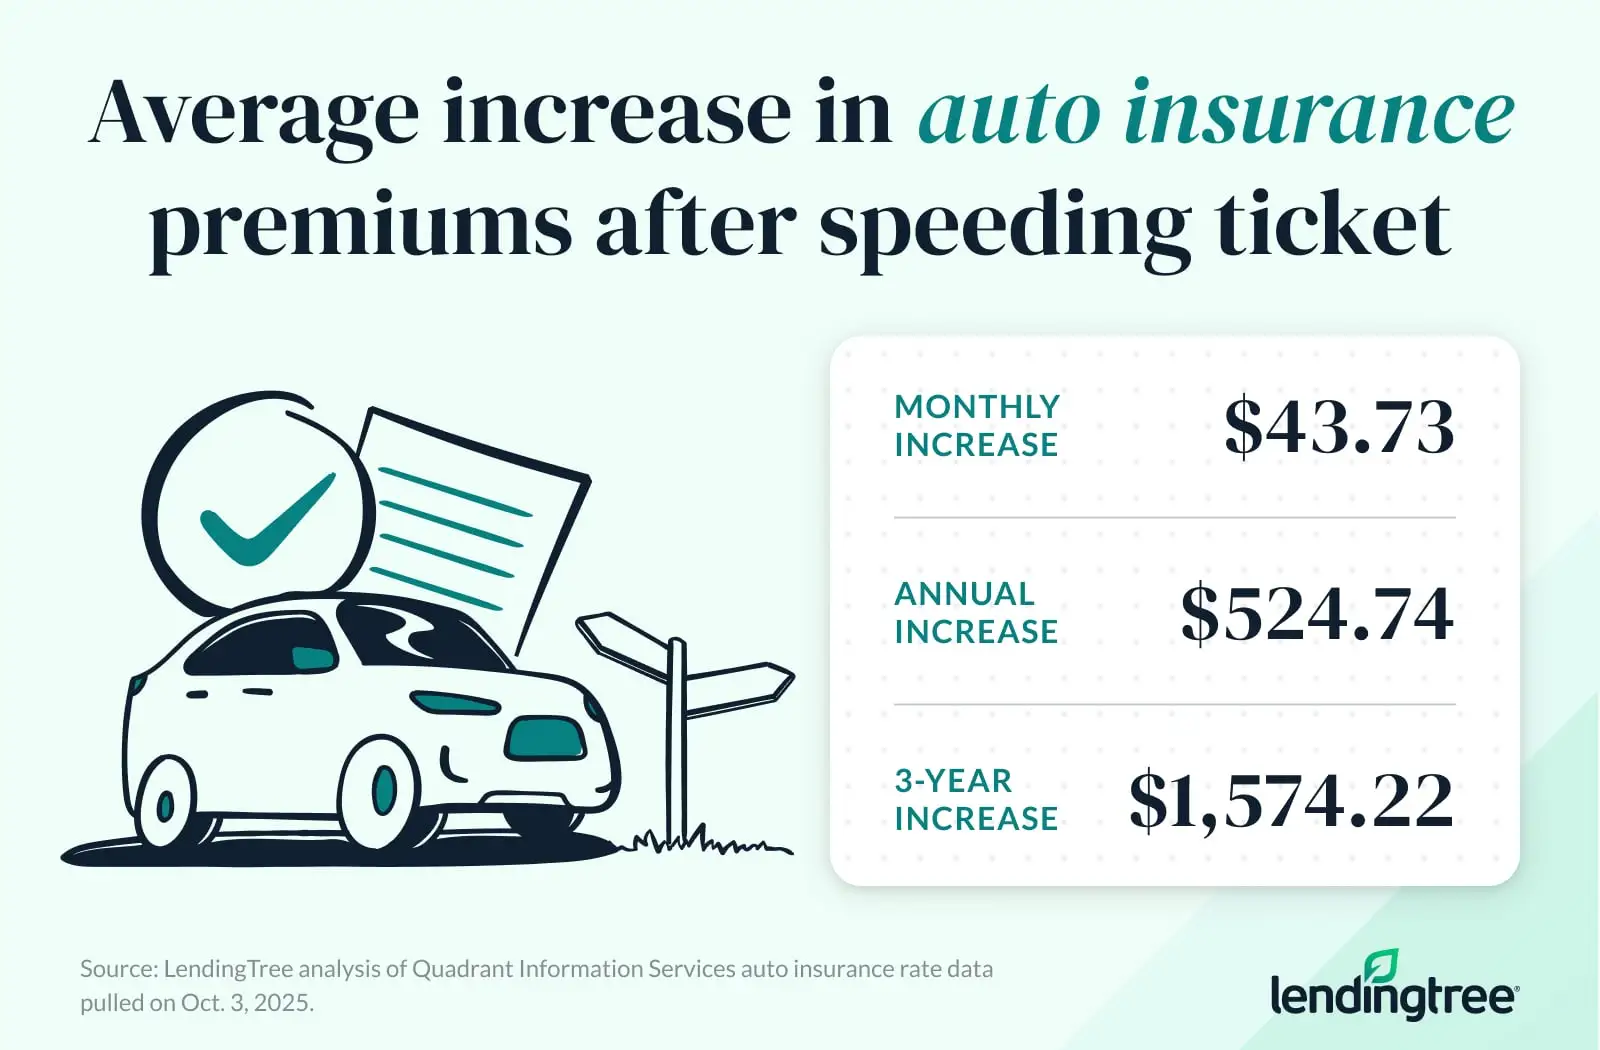 Speeding Tickets Drives Up by Over $500 a Year - LendingTree

